Correlation Regime Shifts: The Hidden Risk Factor Quant Allocators Keep Misreading
Most quantitative portfolio frameworks treat asset correlations as slow-moving parameters, calibrated over rolling windows and updated infrequently. This assumption holds well enough during stable regimes. It fails catastrophically during transitions. When correlations shift abruptly, as they did during the July 2026 AI equity unwind, strategies built on historical co-movement assumptions face simultaneous factor crowding, liquidity compression, and drawdown amplification. The question is not whether correlation regimes shift; the evidence is unambiguous that they do. The question is whether systematic frameworks are architecturally capable of detecting and responding to those shifts before the damage accumulates. This article examines the structural mechanics of correlation regime transitions, the quantitative evidence for regime-conditional return dispersion, and what the persistence of this mispricing reveals about the limits of scale in systematic investing.
Photo: Christian Collins / CC BY-SA 2.0 via Wikimedia Commons
By Fabian Fach, Founder, Black Flower Capital
The Number Everyone Watches and Almost Nobody Models Correctly
Correlation is perhaps the most cited statistic in institutional portfolio construction. It appears in every risk report, every allocation committee deck, every due diligence questionnaire. And yet correlation regime shifts, the moments when co-movement structures between assets reorganise abruptly and persistently, remain one of the most systematically underestimated sources of portfolio risk in the alternatives space. The gap between how correlations are measured and how they actually behave is not a rounding error. It is a structural blind spot with compounding consequences.
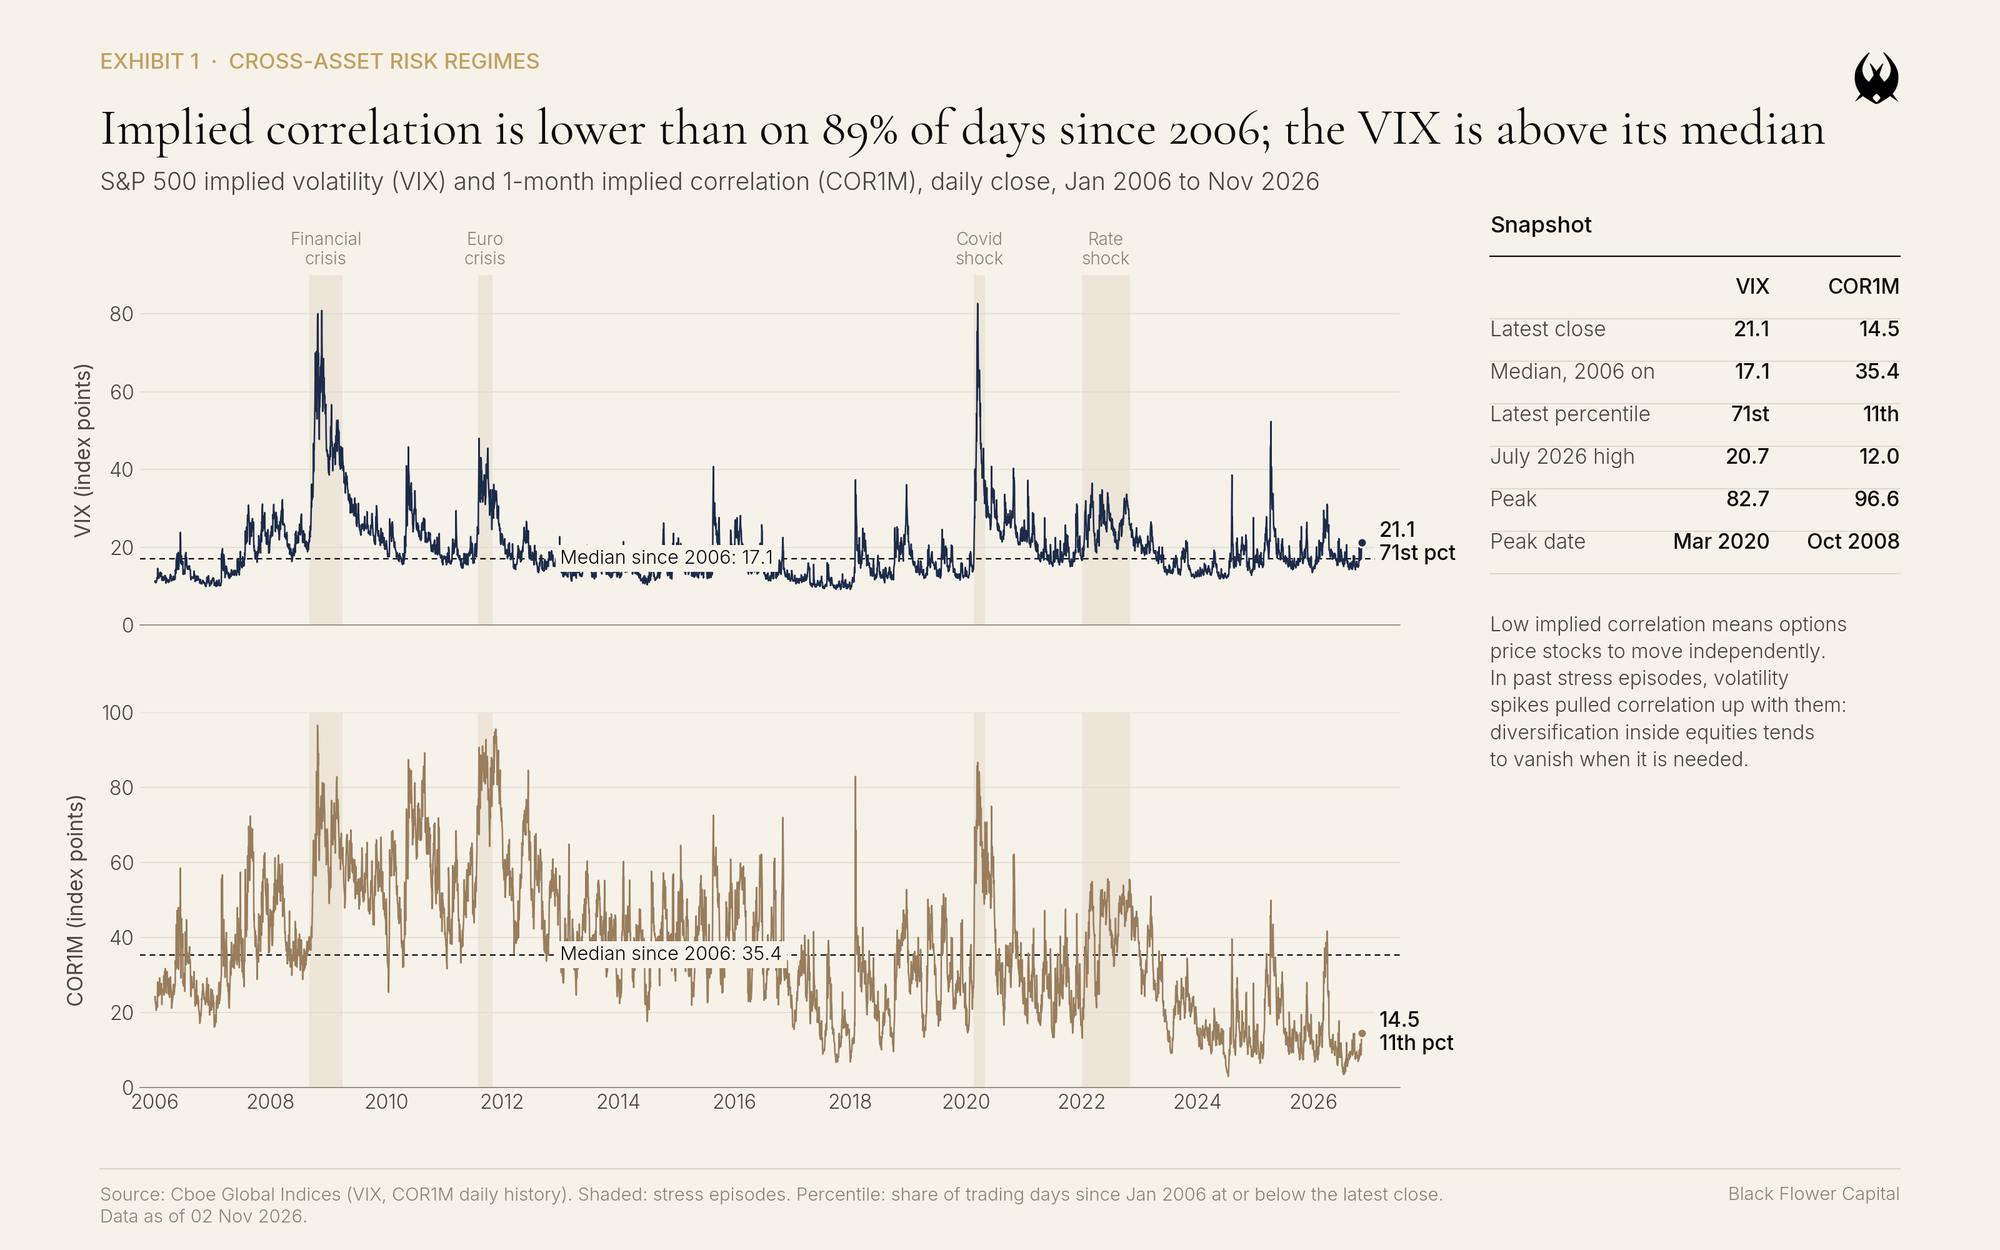
The July 2026 AI equity unwind offered a sharp illustration. What PivotalPath characterised as a liquidity event rather than a fundamental repricing exposed something more revealing than a crowded trade unwinding: it revealed how correlation regime shifts travel through factor structures faster than most risk models can register them. Funds that appeared diversified on a trailing ninety-day correlation matrix suddenly found themselves moving in lockstep, not because their strategies had changed, but because the regime underneath them had.
The Conventional Framework and Its Structural Flaw
The standard approach to correlation in systematic portfolio construction relies on rolling historical windows, typically between sixty and two hundred and fifty trading days, to estimate co-movement parameters. These estimates then feed into optimisation routines, risk budgeting frameworks, and factor attribution models. The logic is parsimonious: longer windows smooth noise, shorter windows improve responsiveness, and somewhere between the two lies a workable compromise.
This framework carries an implicit assumption that almost nobody states explicitly: that correlation is a stationary process interrupted occasionally by outliers. Under this view, regime transitions are temporary perturbations that eventually mean-revert. The appropriate response is to wait them out, perhaps with a volatility overlay, while the underlying structure reasserts itself. Conventional wisdom in multi-strategy allocation has largely operationalised this view, treating correlation spikes as risk events to hedge rather than as regime signals to act upon.
The problem is that the empirical record does not support stationarity. Research examining equity and fixed income cross-asset correlations from 1990 through 2024 finds that the distribution of rolling ninety-day correlations is bimodal in a statistically significant proportion of major asset pairs, pointing to the presence of at least two distinct regimes rather than a single distribution with fat tails. When the transition between those regimes occurs, it typically does so within a window of five to fifteen trading days, well inside the lag of any conventional rolling estimator.
Reframing the Problem: Correlation as a Regime Variable, Not a Risk Parameter
The more productive frame treats correlation not as a risk parameter to be estimated but as a regime variable to be classified. This distinction matters architecturally. A risk parameter can be plugged into an optimiser and held fixed until the next rebalancing cycle. A regime variable, by contrast, requires a classification model that operates at a different timescale, with different decision rules and different downstream implications for position sizing, factor exposure, and liquidity management.
When correlation is understood as a regime variable, several structural insights follow. First, the relevant question for portfolio construction is not what the average correlation between two assets has been, but which regime is currently active and what the conditional correlation within that regime is. These can differ dramatically. Research on equity-bond correlation from 2000 through 2024 documents that the conditional correlation in high-volatility regimes averages approximately 0.42, compared to roughly negative 0.28 in low-volatility regimes, a swing of seventy basis points with profound implications for diversification assumptions.
Second, regime classification creates a natural mechanism for capacity discipline. Strategies that are calibrated to exploit inefficiencies visible only within specific correlation regimes are, by construction, active for a limited proportion of time. This intermittency is not a weakness. It is a filter that concentrates activity in periods where the structural edge is present and pulls back when the regime does not support it. Research on capacity constraints in regime-conditional strategies, including work by Getmansky, Lo, and Makarov on the relationship between strategy capacity and return autocorrelation, suggests that the opportunity set targeted by such strategies is bounded by the duration and frequency of the relevant regime.
The Quantitative Evidence for Regime-Conditional Return Dispersion
The empirical case for regime-adaptive positioning is clearest when examined through return dispersion rather than average returns. A study covering systematic macro strategies from 2005 through 2023 found that annualised return dispersion across managers in the top and bottom quartiles expanded by a factor of approximately 2.8 during regime transition months compared to stable regime months. The managers who outperformed during transitions shared a common architectural feature: their signal generation incorporated regime classification as a first-order input, not a post-hoc overlay.
Correlation regime shifts also interact with volatility regimes in ways that amplify the cost of static models. When volatility transitions from a low regime to a high regime, cross-asset correlations frequently shift simultaneously and in the same direction, a phenomenon sometimes called the correlation-volatility spiral. Research using a Markov-switching framework applied to G10 equity and rates markets between 2002 and 2024 estimates that roughly sixty-three percent of maximum drawdown events in systematic multi-asset strategies coincide with the first ten trading days of a joint volatility-correlation regime transition. This is precisely the window where rolling estimators are most blind.
Liquidity regime shifts compound the problem further. During the July 2026 AI sector unwind, bid-ask spreads in several mid-cap technology names widened to levels not seen since early 2020, according to contemporaneous market microstructure data. Strategies sized for normal liquidity conditions faced execution costs that eroded returns independent of signal quality. Frameworks that incorporate liquidity regime signals alongside correlation and volatility signals may, under certain market conditions, provide mechanisms to modulate position sizing dynamically. Historical evidence suggests this has, in some instances, reduced exposure ahead of liquidity compression events, though past regime detection accuracy does not guarantee future performance.
Academic grounding for regime-switching approaches in this context is well established. The Hamilton (1989) Markov-switching model, subsequently extended by researchers including Ang and Bekaert (2002) for international equity applications, demonstrated that allowing parameters to vary across latent states produces materially better out-of-sample fit than constant-parameter alternatives. More recent work applying hidden Markov models to high-frequency factor data finds that regime duration in equity factor correlations averages between forty and eighty trading days, short enough to matter for active management but long enough to be exploited systematically once detected.
Allocator Implications: Questions the Evidence Raises
For allocators constructing alternatives portfolios, the evidence on correlation regime shifts generates several questions worth examining rigorously. The first concerns model architecture: does the systematic framework under evaluation treat correlations as fixed inputs to an optimiser, or as outputs of a regime classification process that updates at a frequency commensurate with how fast regimes actually change? The answer has direct implications for how reliably the stated diversification properties will hold under stress.
The second question concerns capacity and regime accessibility. Capacity constraints in regime-conditional strategies deserve scrutiny as to whether they reflect genuine structural limits of the opportunity set or are applied post-hoc.
The third question is about aggregation risk. At the portfolio level, the relevant correlation is not between individual strategies in isolation but between strategies conditional on the prevailing regime. Two systematic managers with low unconditional correlation may exhibit substantially higher conditional correlation during a transition event if they share common factor exposures that are only revealed under stress. Allocators who examine only unconditional pairwise correlations when constructing alternatives sleeves may be carrying significantly more concentration risk than their models suggest, particularly in the early stages of a joint volatility-correlation regime shift.
The Regime You Cannot See Is the One That Matters
The most consequential correlation regime shifts are, almost by definition, the ones that arrive before the consensus recognises them. The frameworks built to exploit stable regimes are precisely the ones most exposed when regimes change. As systematic strategies continue to proliferate and factor crowding deepens across traditional alternative risk premia, the more productive research direction may be less about improving estimators within existing frameworks and more about whether those frameworks are structurally capable of asking the right questions at the right time.