Liquidity Regimes and the Capacity Trap: Why Scale Kills the Strategies That Work
The most persistent misconception in quantitative investing is that larger platforms generate superior risk-adjusted returns simply by accumulating talent and capital. The evidence points in the opposite direction. Certain structural inefficiencies in equity and macro markets are not merely difficult to exploit at scale: they become mathematically inaccessible above specific capacity thresholds. Combine this with the reality that volatility and liquidity regimes shift in ways that invalidate static factor models, and the picture becomes clearer: the strategies commanding the most institutional interest are frequently the ones least able to deliver on their premise once assets under management reach critical mass. This article examines the mechanics of capacity constraints, the role of regime detection, and what both mean for how sophisticated allocators should be framing their manager selection questions.
Photo: Gabri80 / Public Domain via Wikimedia Commons
By Fabian Fach, Founder, Black Flower Capital
The Question Nobody in the Room Is Asking
When a major multi-strategy platform announces the hire of a senior quantitative analyst from a global investment bank, the industry reads it as a signal of competitive escalation. More quant firepower, the logic goes, means better alpha extraction. But this framing conceals a more uncomfortable question: at what point does adding capital and talent to a quantitative strategy begin to erode the very inefficiency that made it worth pursuing? Liquidity regimes sit at the centre of this paradox, and most allocators are not examining them closely enough.
The relationship between strategy capacity and liquidity regimes is not academic. It is the mechanism through which many of the most celebrated quantitative return streams quietly degrade. A strategy that generates exceptional Sharpe ratios in a low-liquidity, high-dispersion regime becomes a market-impact problem the moment institutional capital enters at scale. The inefficiency does not disappear. It simply migrates to a capacity threshold below what large platforms can meaningfully deploy.
The Conventional Wisdom and Its Blind Spot
The dominant narrative in institutional allocator circles treats quantitative strategies as scalable infrastructure. The reasoning is intuitive: if a signal is systematic and rule-based, it should replicate across larger notional exposures without fundamental degradation. This view is partially correct for certain categories of strategy, particularly those operating in the deepest, most liquid segments of developed market equities, rates, and foreign exchange. Trend-following CTAs managing tens of billions in futures markets are the canonical example.
But the narrative breaks down the moment it is applied uniformly. Academic literature on return predictability consistently shows that the factors with the highest historical alpha, including short-term reversal, earnings surprise drift in small- and mid-cap equities, and certain microstructure-dependent signals, carry explicit capacity ceilings. Research published in the Journal of Finance found that the aggregate market impact cost of exploiting the short-term reversal effect in U.S. equities rendered the strategy effectively uneconomic for institutions managing more than a few hundred million dollars in the relevant exposures, across the period 1993 to 2019. The signal is real. The access is not democratically available.
This is not a minor footnote. It is a structural feature of how alpha generation actually works. The conventional wisdom that more capital equals more research capability equals better returns systematically ignores the denominator: the finite pool of exploitable inefficiency available at any given capacity level and in any given market regime.
Regime Detection as the Missing Variable
Frame the problem differently and the structure becomes clearer. Markets do not operate in a single equilibrium state. Volatility regimes, correlation regimes, and liquidity regimes shift over time, and they do not shift uniformly across asset classes or strategy types. A factor that is highly predictive during a low-volatility, high-liquidity regime may carry entirely different risk-adjusted characteristics when the market transitions into a stress or dislocation state.
This is where regime-aware systematic approaches diverge from static factor models. Rather than assuming that historical relationships persist unconditionally, regime-sensitive frameworks attempt to identify the current market state along multiple dimensions simultaneously: realised versus implied volatility spreads, cross-asset correlation clustering, bid-ask spread dynamics as a liquidity proxy, and the behaviour of funding markets as a stress indicator. The goal is not prediction of regime transitions, which remains a genuinely hard problem. The goal is adaptive positioning that reduces exposure to factors known to behave poorly in specific regimes while maintaining or increasing exposure where the regime is historically supportive.
The practical implication is significant. A strategy running a fixed factor exposure across all market states will average out its performance across regimes that are fundamentally different in character. A regime-aware approach that systematically adjusts exposure based on observable market signals will, over a full cycle, reduce the frequency of being long a factor precisely when that factor's alpha generation is structurally suppressed. Liquidity regimes, in particular, are measurable with reasonable precision and carry strong empirical relationships with factor performance across asset classes.
Mechanics, Evidence, and the Numbers That Matter
The empirical case for regime-conditional factor performance is well-established in the academic literature. A widely cited study by Asness, Moskowitz, and Pedersen, examining momentum and value strategies across global equity, fixed income, commodity, and currency markets from 1972 to 2011, documented that liquidity risk is a systematic component of factor returns across all asset classes examined. Strategies perform markedly differently depending on whether funding liquidity conditions, proxied by the TED spread and other short-term funding indicators, are in an expansionary or contractionary state.
More granularly, research from the Journal of Financial Economics on the interaction between market liquidity and equity factor returns showed that the profitability of size and momentum factors in U.S. equities from 1963 to 2015 was significantly concentrated in periods of stable or improving liquidity conditions. During liquidity-constrained episodes, the same factors exhibited both higher volatility and reduced predictive power, with Sharpe ratios dropping by approximately 40 to 60 percent in the worst liquidity quartile relative to the best. This is not noise. It is a structural feature of how price discovery works under different funding conditions.
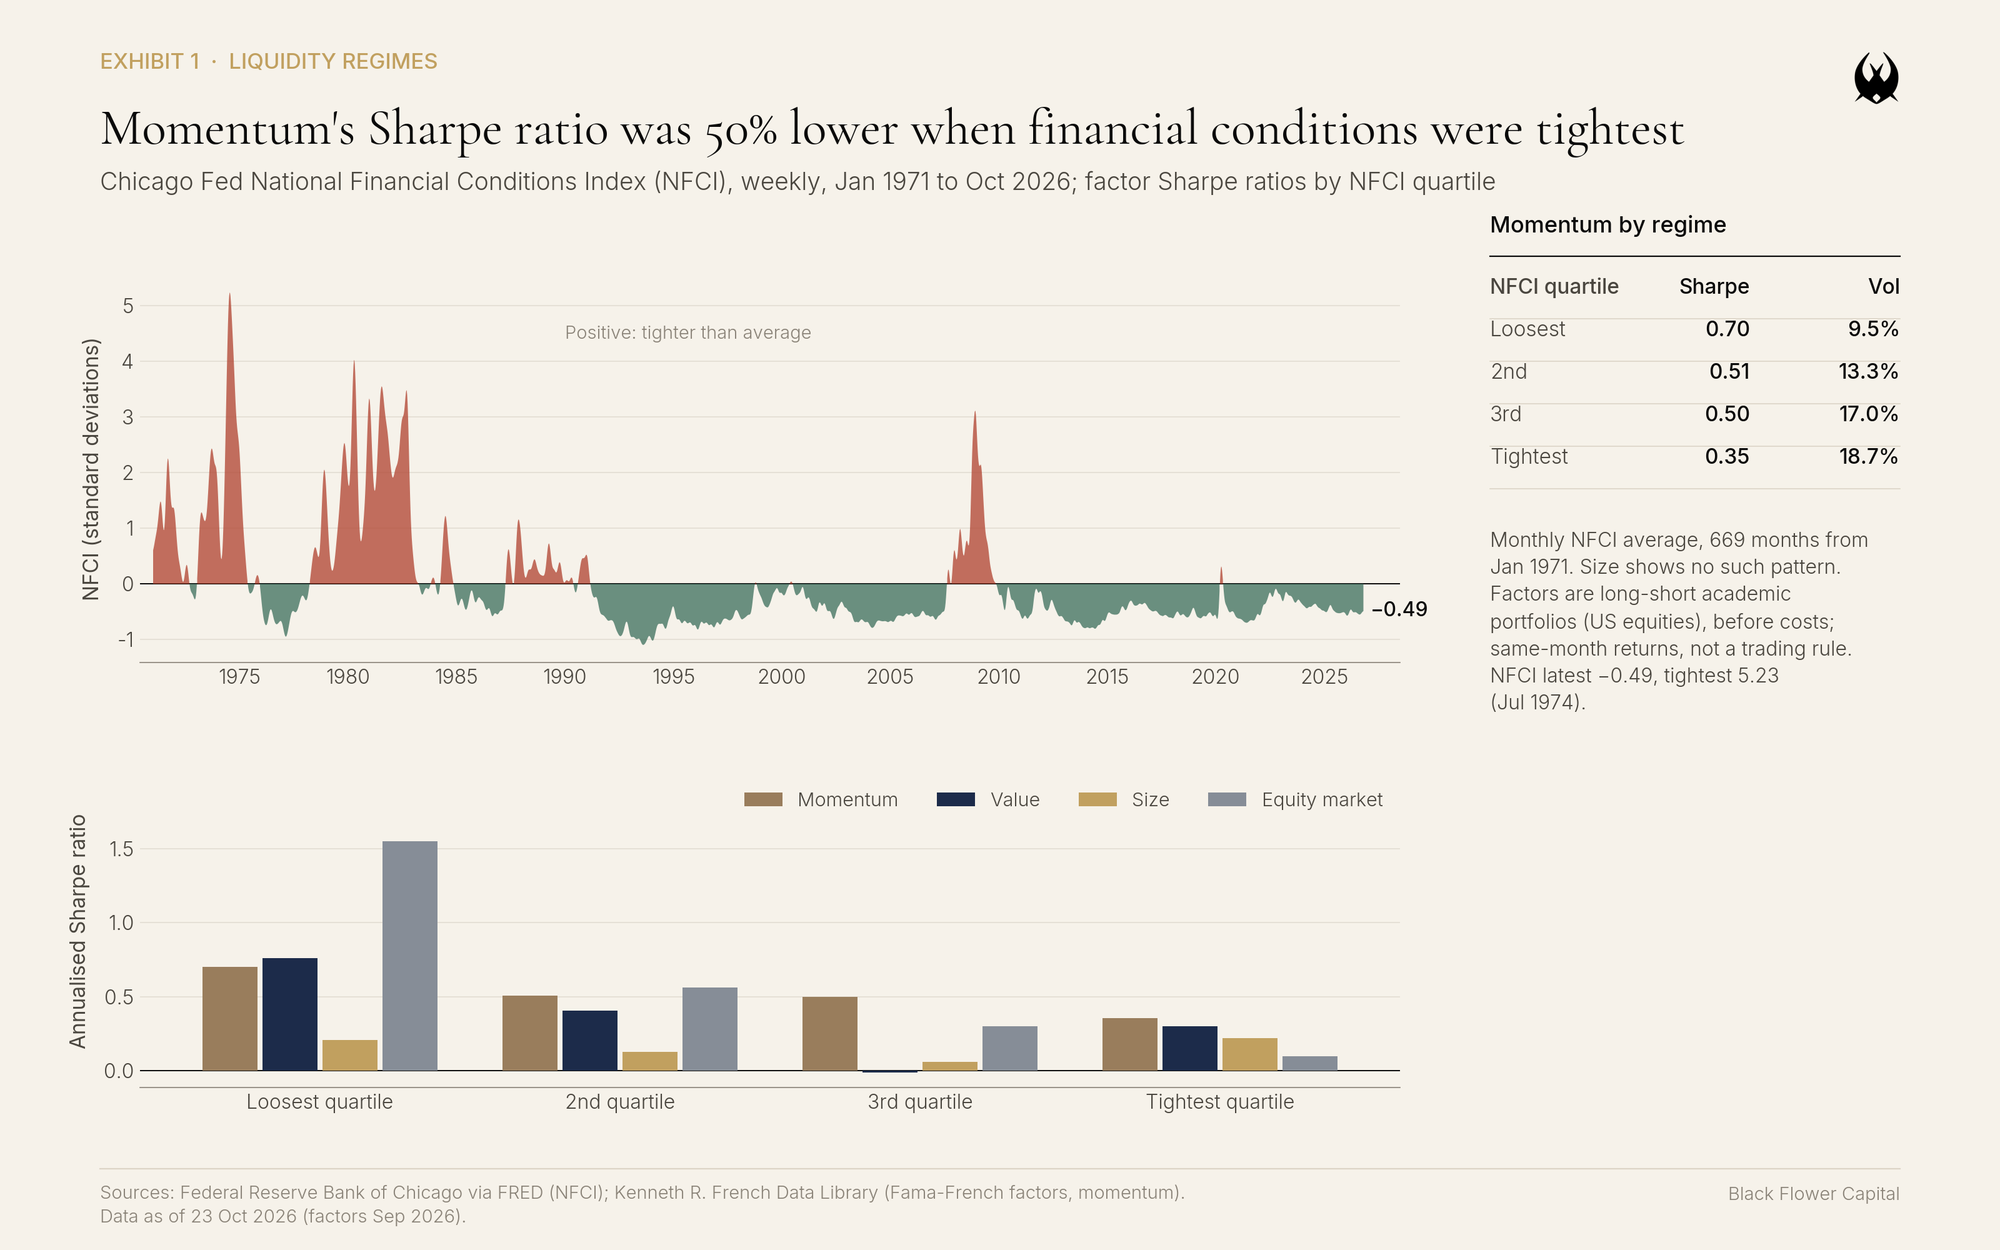
Capacity constraints interact with this regime dependency in a compounding way. A strategy that is already operating near the upper boundary of its exploitable capacity faces a particularly acute version of the liquidity regime problem. In a normal liquidity environment, market impact is manageable. In a liquidity-constrained regime, bid-ask spreads widen, market depth deteriorates, and the same strategy faces both higher execution costs and reduced signal quality simultaneously. Large platforms can absorb this through diversification across many sub-strategies, but the capacity problem in individual strategy sleeves does not disappear, it is simply aggregated and sometimes obscured.
For strategies operating well below their capacity ceiling, the regime transition problem looks different. The smaller footprint means lower market impact during stress periods, but regime awareness remains essential for a different reason: sizing decisions made under a false assumption of regime stationarity will systematically overweight positions precisely when the supporting conditions are deteriorating. Detection frameworks that update continuously based on observed market signals, rather than backward-looking model calibration windows, provide a structural advantage in managing this risk.
What Allocators Should Be Examining
For institutional allocators constructing portfolios of alternative strategies, the questions that follow from this analysis are specific. First: at what asset under management level does each systematic strategy in the portfolio begin to experience material factor decay, and is that threshold documented and monitored? Managers with genuine conviction in their capacity discipline will have explicit answers, typically grounded in transaction cost analysis and signal half-life modelling. Managers who respond with vague references to scalability are signalling something important.
Second: does the manager's framework explicitly condition positioning on regime state, and if so, which dimensions of regime are being measured? The choice of regime indicators is not arbitrary. Frameworks that rely solely on realised volatility as a regime signal are underspecified. Liquidity regimes in particular, as the evidence above suggests, carry independent predictive power for factor performance that is not fully captured by volatility measures. An allocator assessing a systematic manager's regime awareness should probe the specific mechanics: what triggers a regime reclassification, what is the lag structure of the response, and how is the framework validated out-of-sample?
Third: how does the manager's capacity discipline interact with the allocator's own liquidity requirements? Strategies that are capacity-constrained by design, operating in less liquid segments of equity or credit markets, carry different redemption dynamics than their large-cap systematic counterparts. Understanding the liquidity mismatch between the underlying strategy and the fund structure is an allocator responsibility, not merely a legal disclosure exercise.
The Question the Next Cycle Will Force
As quantitative talent continues to concentrate in the largest multi-strategy platforms, and as those platforms deploy increasingly sophisticated analytical infrastructure, a structural irony is building: the best systematic ideas may be most precisely identified by the institutions least positioned to exploit them at economic scale. The next liquidity regime dislocation will test whether scale is an advantage or an impediment, and the answer is unlikely to be uniform across strategy types. The more productive question for allocators is not which manager has the most quant talent, but which systematic frameworks are deliberately sized to remain inside the boundaries where their edge actually lives.