Volatility Regime Detection: The Signal That Systematic Macro Gets Right When Discretionary Traders Don't
Most macro investors believe they manage risk by sizing positions according to volatility. They are solving the wrong problem. The real variable is not current volatility but which volatility regime the market is transitioning into next. Regime detection, when implemented systematically, does not merely adjust position size. It reconfigures the entire structure of a portfolio: which instruments carry signal, which correlations are stable, and which liquidity assumptions have already broken down. This article examines why volatility regime detection is structurally underdeveloped in discretionary macro, how adaptive systematic frameworks exploit that gap, and what the evidence from cross-asset momentum and correlation breakdowns reveals about portfolios that fail to account for the regime they are actually trading in.
Photo: Stanley Kubrick / LOOK Magazine / Public Domain via Wikimedia Commons
By Fabian Fach, Founder, Black Flower Capital
The Question Nobody Asks at the Top of a Trend
When a macro trade is working, the instinct is to ask how much further it can run. The more important question is whether the volatility regime that made the trade possible is still intact. These are not the same question, and confusing them is one of the more expensive errors in institutional portfolio management. Volatility regime detection is not a refinement of risk management. It is a prerequisite for understanding whether the signals being traded are even valid.
The distinction matters because most macro frameworks treat volatility as an output, something to monitor after a position is on. Systematic approaches that embed volatility regime detection as an input, conditioning position construction on regime state before the trade is initiated, occupy structurally different territory. The evidence for this distinction is not anecdotal. It is measurable, repeatable, and largely invisible to managers whose frameworks are not built to look for it.
Conventional Wisdom and Its Comfortable Blind Spot
The standard narrative in macro investing holds that diversification across asset classes, geographies, and themes provides sufficient regime resilience. A book that spans rates, currencies, commodities, and equities, the argument goes, will not be uniformly wrong in any single environment. This is a reasonable prior. It is also incomplete in a specific and consequential way.
Cross-asset diversification is correlation-dependent, and correlations are themselves regime-dependent. During the 2022 simultaneous drawdown in global equities and sovereign bonds, the diversification assumption that had held for roughly four decades collapsed within a single calendar year. Managers running balanced macro books discovered that their hedges were not hedges at all: they were additional expressions of the same duration and inflation surprise risk. The portfolio was diversified in label. It was concentrated in factor.
The conventional response to such events is to describe them as tail risks or regime breaks and to adjust narratively. The more useful response is to ask whether a detection framework existed that could have identified the regime transition before the correlation structure collapsed, not after. For most discretionary macro books, the honest answer is no. The regime break was identified retrospectively, through performance attribution rather than prospective signal.
Reframing the Problem: Regime as the Asset Class
A more productive frame treats the volatility regime itself as the primary variable being traded, with specific instruments as the implementation layer. In this view, the question is not whether rates should be long or short in isolation. The question is what the current regime implies about which instruments carry reliable signal and which are likely to generate noise.
This reframing has structural implications. Low-volatility regimes and high-volatility regimes do not simply differ in the magnitude of price moves. They differ in the instruments that exhibit trend persistence, the correlations that are stable versus spurious, and critically, the liquidity conditions that govern execution costs. A systematic framework that detects regime state and reconfigures its instrument universe accordingly is doing something qualitatively different from a framework that applies fixed position-sizing rules across all conditions.
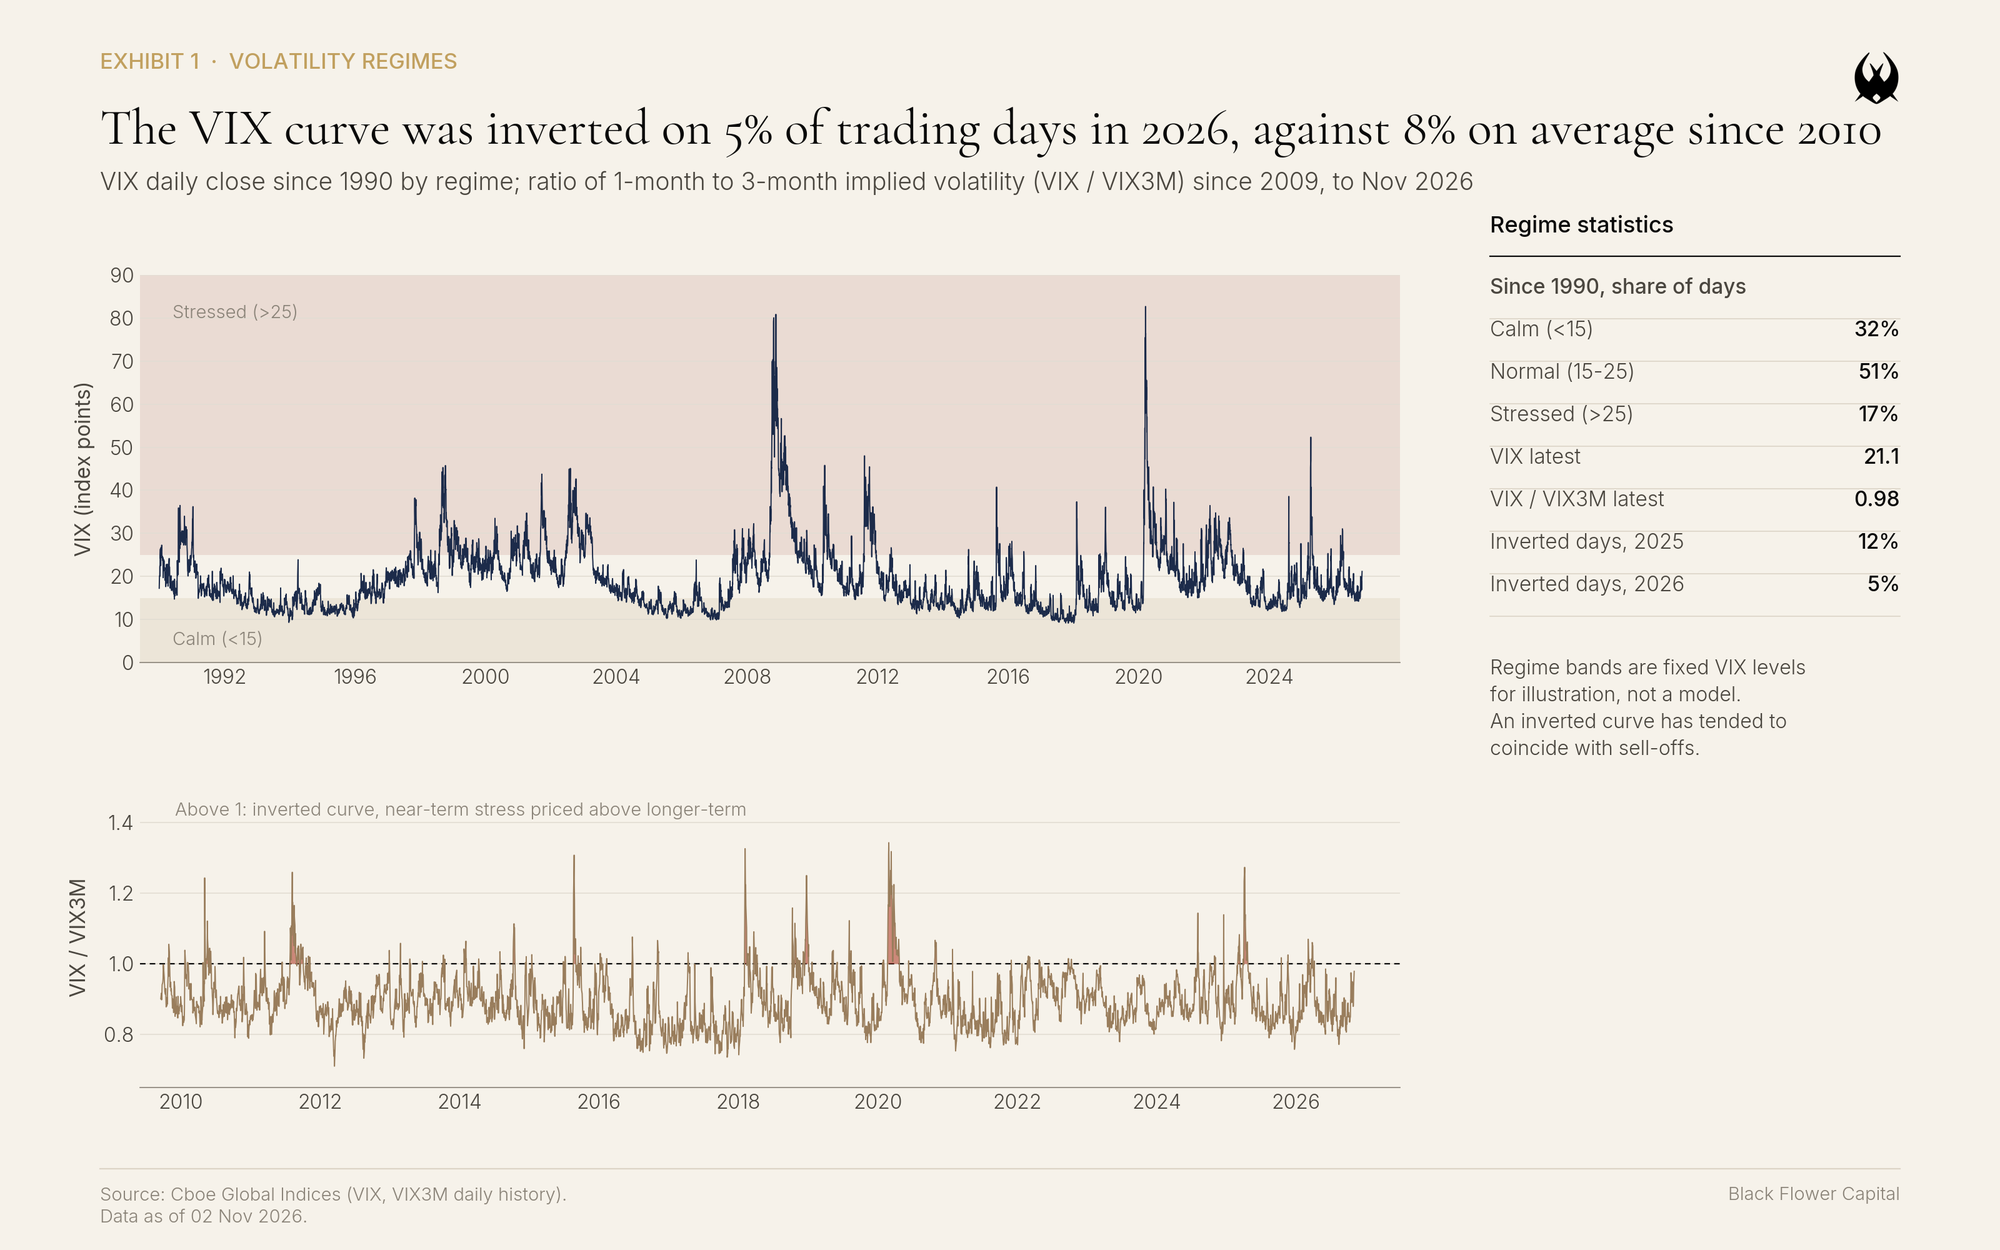
The practical consequence is that volatility regime detection functions as a filter on the opportunity set, not merely on the risk budget. Instruments and strategies that generate consistent signal in one regime can become statistically indistinguishable from noise in another. Managers who do not account for this are not simply taking more risk in bad environments. They are trading on degraded signals without knowing the degradation has occurred.
What the Evidence Shows
Research on cross-asset momentum strategies documents a consistent pattern: trend-following signals in equity index futures, currency forwards, and commodity futures exhibit meaningfully different Sharpe ratios across volatility regimes, even controlling for the mechanical relationship between volatility and raw returns. Academic research, including Hurst, Ooi, and Pedersen (2017) on two centuries of trend-following returns, documents that risk-adjusted performance in identified low-volatility regimes with stable cross-asset correlations outperforms high-volatility fragmented-correlation environments by margins that cannot be explained by position sizing alone.
The correlation structure finding is particularly important. Hurst, Ooi, and Pedersen (2017), along with subsequent work building on that framework, identifies distinct clustering in cross-asset correlation regimes: periods where correlations are stable and forecastable, and periods where they are elevated and unstable. The transition between these states tends to precede volatility spikes by several weeks rather than coinciding with them. A detection model that tracks correlation dispersion as a leading indicator of regime change provides signal that pure volatility measures miss.
The capacity dimension of this finding deserves attention. The strategies that exploit regime transitions most efficiently tend to operate in markets where position sizes relative to average daily volume are small enough to avoid self-impacting the signal. As assets under management in a given strategy grow, the executable alpha from rapid regime repositioning compresses. This is not a theoretical concern. Based on CFTC Commitments of Traders data from 2015 to 2025, large systematic managers (those managing in excess of ten billion dollars in trend-following alone) appear to exhibit slower regime adaptation than smaller vehicles, a pattern that may be consistent with liquidity-driven execution constraints, though the open-interest data alone cannot establish this causal relationship definitively.
Large multi-strategy platforms that have raised significant new capital in recent cycles illustrate this dynamic at scale. Larger aggregations of capital generate their own capacity problem, not necessarily in any single strategy, but in the aggregate pressure placed on the rebalancing trades required to shift regime positioning. The friction is diffuse and therefore difficult to attribute, but it is present in transaction cost analysis across regime transition periods.
Allocator Implications
The analytical questions for allocators evaluating systematic macro strategies centre on specificity rather than category. The relevant distinction is not between systematic and discretionary macro as broad labels, but between regime-aware and regime-agnostic implementation within the systematic category. A strategy that applies a single signal generation framework regardless of whether it is operating in a low-volatility trending regime or a high-volatility mean-reverting regime is not adaptive in any meaningful sense: it is simply unleveraged relative to its own risk model.
Allocators should examine whether a manager's drawdown profile clusters around regime transitions or around idiosyncratic model errors. The former suggests a regime-detection gap. The latter suggests execution or signal quality issues. These are different problems requiring different due diligence responses. Regime-transition drawdowns that are deep and slow to recover are the signature of a framework that was not repositioned until after the environment had already changed: the detection lag is embedded in the loss profile.
The capacity question is equally worth examining with precision. A systematic macro strategy that operates across a constrained set of instruments with meaningful position size relative to daily volume has a fundamentally different capacity ceiling than a strategy that operates across broad, liquid futures markets. The former may exhibit stronger risk-adjusted returns at smaller scale precisely because it accesses structural inefficiencies that cannot survive position scaling. Allocators building macro exposure across multiple vehicles should consider whether their aggregate systematic macro allocation is, in effect, accessing the same regime sensitivity from multiple sources or genuinely diversifying across regime detection methodologies.
The Forward Question
As central bank policy frameworks become less predictable and cross-asset correlations remain structurally less stable than in the pre-2022 period, the question for every macro allocator is not which direction rates or currencies are heading. The question is whether the frameworks in their portfolio are detecting the regime they are actually in, or the one they were positioned for three weeks ago.