The Circular Trillion: How AI's Biggest Balance Sheets Became Each Other's Collateral
Anthropic is reportedly seeking a $2 trillion IPO valuation while Nvidia, the company actually supplying the chips underneath that number, trades near its cheapest levels in over a decade. Underneath that gap sits a tighter structure than it first appears: SoftBank, OpenAI, Nvidia, SB Energy, Amazon, and Google are increasingly buying from, lending to, and marking up the same handful of counterparties, including each other.
Photo: Fleshas / BalticServers.com, CC BY-SA 3.0 via Wikimedia Commons
By Fabian Fach, Founder, Black Flower Capital
Anthropic is reportedly seeking a $2 trillion valuation for an IPO that keeps getting pushed back. Nvidia, the company actually shipping the hardware every AI lab depends on, is trading near its cheapest level in over a decade. That gap between the picks-and-shovels seller and the company still digging is the headline. The more interesting story sits one layer down: how much of the growth propping up that $2 trillion number is the same handful of companies buying from, lending to, and revaluing each other.
The Financing Loop Behind the Headline Number
Start with the plumbing. SB Energy, SoftBank's data center developer, is trying to go public at a $50 billion valuation despite not having switched on a single facility, largely on the strength of a 20-year lease to OpenAI at a campus in Pike County, Ohio. Nvidia has agreed to guarantee up to $105 billion of that campus's lease and power obligations in exchange for the site running exclusively on Nvidia chips for two decades, and has already put $1.5 billion of its own money into SB Energy ahead of the listing.
Meanwhile, Amazon's most recent quarterly profit included a $53.4 billion gain, primarily from its Anthropic stake, roughly two-thirds of its pre-tax income for the period. Alphabet's $62.6 billion first-quarter profit, a record when it was reported, included about $28.7 billion from revaluing its private-company stakes, primarily Anthropic, nearly half the total. In the second quarter, gains on equity securities came to $99.0 billion of a $112.2 billion profit. Neither dollar came from selling anything.
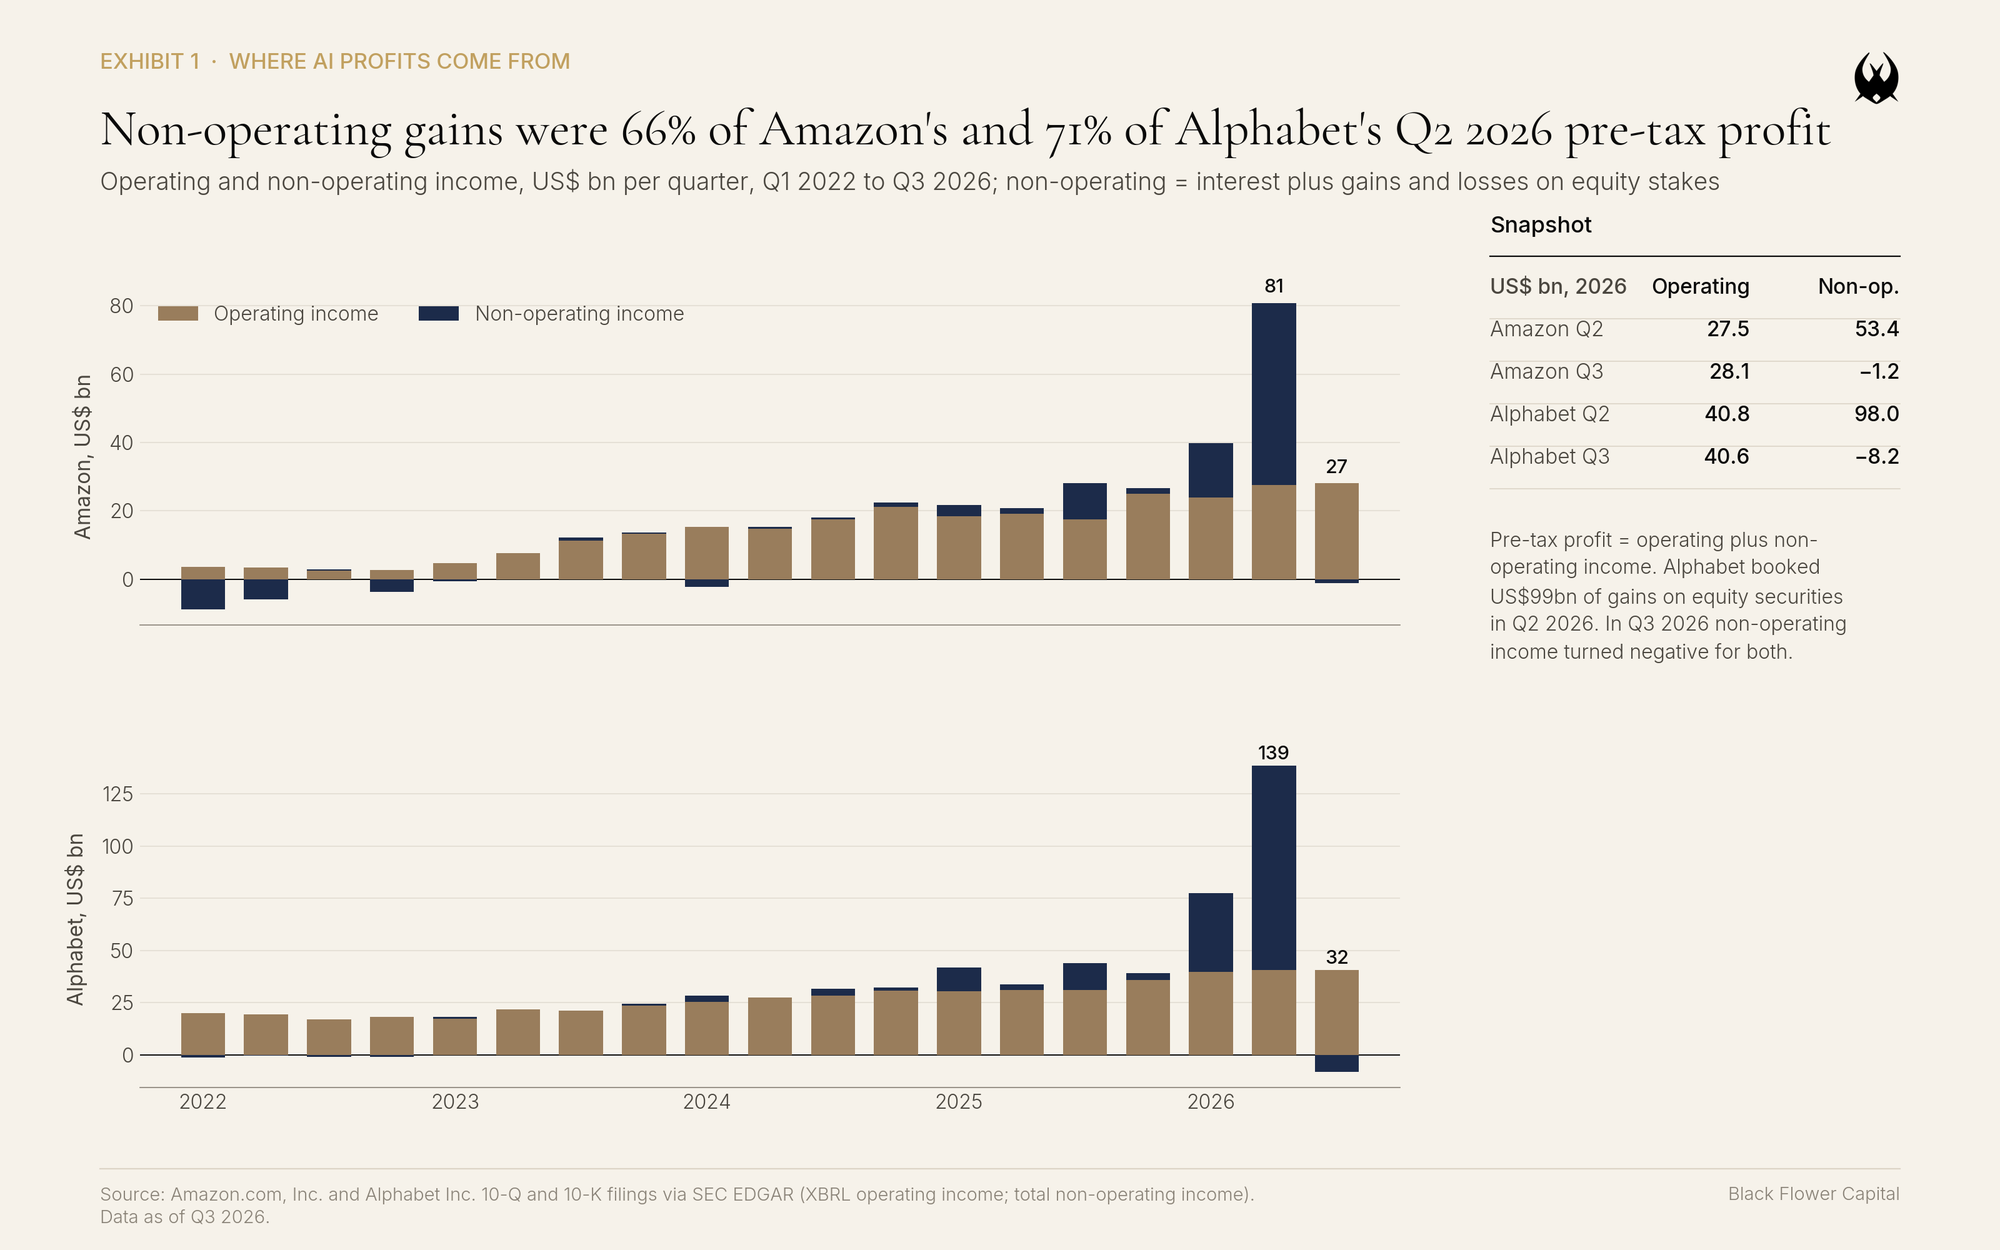
None of this is a rumor. It comes out of the companies' own filings, bond prospectuses, and reported results. It is also, on its own terms, a completely rational way for each individual company to behave. The problem is not any single link in the chain. It is what happens when every quarterly report counts its own link as an independent source of strength.
The Question That Matters More Than the Price Tag
The usual read on this is valuation skepticism: is $2 trillion too much to pay for a company still burning cash. That is a fair question, and it gets asked often enough. The question that matters more for anyone managing risk across a portfolio is different: how many of your supposedly separate return streams are actually the same trade wearing different tickers.
Amazon's earnings, Google's earnings, Nvidia's revenue growth, SoftBank's balance sheet, and the private valuations of Anthropic and OpenAI are not five independent data points right now. They are one financing structure, distributed across five income statements. If AI capital expenditure keeps accelerating, all five get marked up together. If it stalls, the marks reverse together, the leases get renegotiated together, and the debt gets repriced together, because they were never actually separate credit or equity risks to begin with. They only look separate because they sit on five different quarterly reports, a version of reflexivity in which the valuation and the fundamentals it is supposed to reflect are being generated by the same closed loop.
Why the Least Productive Phase of the Buildout Looks Best on Paper
The Accounting Quirk in Unfinished Infrastructure
The specific mechanism worth understanding is what happens to an asset before it is finished. A data center under construction sits on the balance sheet as construction in progress, which is not depreciated. Chips that have been purchased but not yet switched on are not depreciated either. The least productive phase of this entire buildout, the phase with no revenue, no output, and no customer complaints about latency because there is no product yet, is also the most accounting-friendly phase. Depreciation only starts once the asset turns on and begins aging, at precisely the moment it starts producing the revenue that was supposed to justify the valuation.
The Debt Stacked on Top of It
Layer debt on top of that, at two levels. SB Energy's own backlog-related capital expenditure commitments run to roughly $178 billion against a $50 billion IPO valuation target. Its parent, SoftBank Group, financed part of its own AI push, including a further payment into OpenAI, through an $11.1 billion bond sale this month, the largest high-yield corporate bond offering on record globally, with one tranche pricing at 9.75 percent, the highest yield SoftBank has ever paid on dollar debt. That is a parent company borrowing at distressed-adjacent rates to keep funding a subsidiary that has not switched on a single data center yet. SB Energy's own risk disclosures note that if a project runs late, its customer can in some cases buy the asset outright, at a discount. Its main customer is OpenAI.
A Product That Is Getting Cheaper Every Quarter
There is a second, quieter pressure working against the same structure: the price of what these labs actually sell is falling fast. Independent research from Epoch AI estimates that the cost of getting a given level of AI performance has dropped roughly thirteenfold a year since 2023, faster than the historical pace for electricity, computing, or DNA sequencing. Cheaper open-weight models are closing the performance gap quickly enough that Anthropic and OpenAI both cut prices on the same day this month. A structure built on long-dated debt and un-depreciated infrastructure is more fragile, not less, when the product financing all of it gets cheaper every quarter.
What This Means for a Portfolio That Thinks It's Diversified
None of this means the AI buildout is fake or that the technology will not matter. Infrastructure spending in 1999 was real too, and the internet did change the world; it just did not save the equity holders of every company that built it. What it means is narrower and more useful: a portfolio that holds public mega-cap tech, private credit exposure to data center developers, and venture-style stakes in AI labs, believing those to be three separate risk buckets with three separate return drivers, is currently holding one exposure wearing three different wrappers. That is the same failure mode covered in our diversification illusion piece on chip-stock concentration, applied one layer further down the balance sheet. The correlation between them is not a tail-risk scenario waiting to happen. It is already built into how each of these entities marks its own books today, every single quarter, which is exactly why asset correlations are worth re-checking rather than assuming they hold.
That matters most for whichever sleeve of a portfolio is supposed to do the opposite of what the rest of it does when conditions turn. A hedge that is meant to be uncorrelated to an equity drawdown does not do its job if it turns out to share the same underlying dependency, just dressed up as private credit, a strategic equity stake, or a vendor financing guarantee instead of a plain index allocation. Genuinely uncorrelated exposure does not care whether the shared dependency this cycle is called AI capital expenditure or something else entirely next cycle. It cares whether the dependency is actually shared, and across a meaningful and growing slice of both public and private markets right now, it clearly is. Real diversification means checking what an asset is actually exposed to, not just what shelf it sits on in a portfolio report.
The Question Worth Asking About Your Own Book
Ask your own book a simple question: if AI capital expenditure growth slowed materially for eighteen months, how many of your supposedly different positions would move for exactly the same reason, at exactly the same time. If the honest answer is more than feels comfortable, the diversification you thought you were holding was mostly an illusion created by counting the same trade five times under five different names. The market has not priced that risk yet. The five companies doing the counting have every incentive to make sure it takes a while before it does.